

TransUnion®

- 3.06K Reviews
- 3.2
- Downloads
- 1,000,000+
Our take on TransUnion® from Appgk
When I look at a finance app, I want a clear answer to a practical question: will it help me understand and manage my credit without creating more confusion? TransUnion® is built around that purpose. It brings together access to credit scores, credit reports, and related offers in one mobile experience, making it more useful as a regular check-in tool than as a complete personal-finance command center.
I approached it as someone who wants to monitor credit calmly, spot changes early, and decide whether an offer deserves attention. The app is free, aimed at everyone, and developed by TransUnion Interactive, Inc. Its current version is 5.8.0, and the service has been available since Jan 8, 2014. That long presence matters, although the average rating of 3.2 from around 8,400 ratings suggests the experience is not equally smooth for every user.
What I would check before choosing a credit app
My first decision criterion is the job I actually need done. If I want to see my credit information in one place, this app makes sense. If I want detailed budgeting, bill negotiation, investment tracking, or a full financial dashboard, I would start looking at a different category. TransUnion® is focused rather than broad, and that focus is both its appeal and its boundary.
The second question is whether I will use the information actively. A report is not valuable merely because I opened it once. I would use the app before applying for a major financial product, after moving or changing accounts, and whenever something on my credit profile looks unfamiliar. The useful habit is not checking constantly; it is checking with a reason and recording what changed.
Best Parts of TransUnion®
Things to Keep in Mind About TransUnion®
I also care about how much interpretation an app provides. Credit information can be difficult to read when several accounts, inquiries, balances, and status labels appear together. A convenient score view may be helpful for a quick read, but a report deserves slower attention. I would not treat a single number as a complete verdict on my financial health.
Finally, I would separate monitoring from decision-making. Offers shown inside a finance app can be convenient, but convenience does not make an offer suitable. I would compare the full terms elsewhere before accepting anything, especially when borrowing costs or long-term commitments are involved.
News and Features Related to TransUnion®

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
A practical first setup
My recommended starting routine is simple. Install the app, complete the account and identity steps carefully, then review the score area before opening every available offer. Next, move through the report with a specific checklist: unfamiliar accounts, unexpected inquiries, incorrect personal details, and statuses that do not match my records.
I would take notes outside the app about anything that needs follow-up. This is one of the less obvious ways to get more value from a credit-monitoring tool: the app can show information, but a personal timeline helps me remember when I noticed it and what action I took. That turns a passive glance into an organized process.
Don't want to read the full review?
I would also avoid checking immediately after every financial change and assuming the display must update at once. Credit information can move through reporting cycles, so a recent payment or account change may not appear when I expect. The sensible approach is to use the app as an important reference, not as an instant transaction ledger.
Where TransUnion® wins in everyday use
The strongest part of the experience is the combination of scores and reports. I do not have to treat a score as an isolated number and then search for context in a separate place. Moving from the headline result to the underlying report is the workflow I find most useful, because it encourages me to ask why the number looks the way it does.
Screenshots
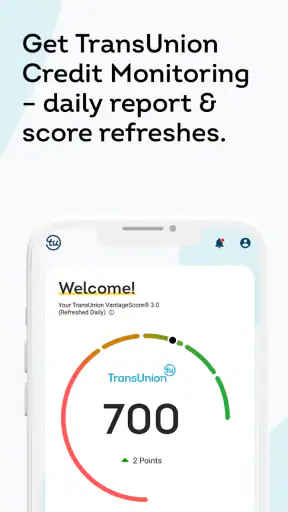
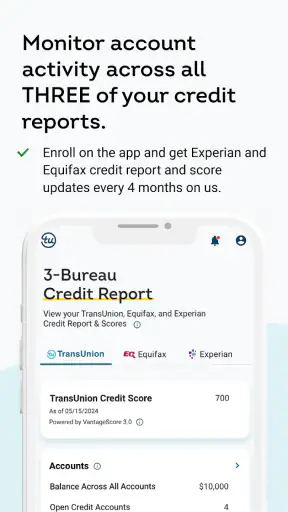
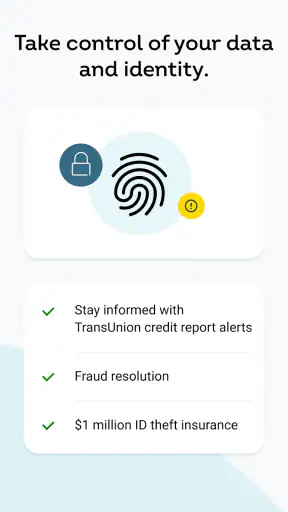
The offers area can also be handy when I am already researching a financial product. Instead of beginning with a completely blank search, I can use the app as one starting point for understanding what is being presented to me. I would still compare alternatives, but having that information near my credit view can make the research process more structured.
Another advantage is accessibility. With over one million installs, the app is clearly familiar to a substantial Android audience, and its Everyone content rating makes it approachable for a wide range of users. That does not guarantee that every screen will feel effortless, but it supports the idea that this is intended for ordinary people checking their credit, not only for finance enthusiasts.
In my view, the app is especially good for someone who has never developed a credit-monitoring routine. The focused layout of scores, reports, and offers gives that person a concrete place to begin. I would rather recommend a focused tool that someone will actually open than a more ambitious financial app that feels overloaded and gets ignored.
The everyday scenario where it earns its place
Imagine I am preparing to rent a new apartment. Before speaking with a landlord, I open the app and review my score and report. I notice an account entry that I do not recognize. Instead of discovering the issue during an application, I have time to investigate my records and prepare an explanation or dispute through the appropriate process.
That scenario shows the app’s real value: preparation. It is not promising to solve every credit problem from one screen. It gives me an earlier view of information that may affect a decision, which can reduce unpleasant surprises. I would use it in the same way before a car purchase, a refinancing conversation, or any situation where my credit history is likely to matter.
There is a second useful workflow for people rebuilding credit. I can review the report, identify the accounts that need attention, and return later to see whether the overall picture has changed. The important trade-off is patience. The app can help me observe progress, but it cannot replace on-time payments, sensible borrowing, or correcting inaccurate records.
Small habits that make the app more useful
I would avoid opening only the score card. The report is where I can find the clues behind a change, so I would make it part of the routine whenever the score moves unexpectedly. This is more informative than reacting to a number without knowing which account or inquiry influenced it.
I would also treat offers as research prompts rather than recommendations. If an offer catches my eye, I would write down the important terms, compare them with other choices, and consider whether I need the product at all. This habit protects the main benefit of the app—awareness—without letting the offers dictate my financial decisions.
A third useful habit is to review personal information for accuracy, not just account balances. An incorrect address or identity detail can make a report harder to understand and may complicate future applications. I would keep my own records nearby so I can distinguish an unfamiliar entry from one I simply forgot about.
The app is free, which removes an obvious barrier to trying it. Still, “free” should not be confused with “free of trade-offs.” My time, attention, and willingness to compare offers are still part of the cost. If I use the app casually and accept whatever appears first, I lose much of the control that a credit-monitoring tool is supposed to provide.
What may feel less comfortable
The rating of 3.2 is a useful warning to keep expectations realistic. I would not install this expecting a flawless experience on every device or in every account situation. Finance apps can be particularly frustrating when sign-in, identity checks, report access, or data refreshes do not behave as expected, and I would allow time for troubleshooting rather than relying on the app during a last-minute application.
The focused scope may also feel limiting. I cannot use a credit-reporting app as a substitute for a household budget, a spending tracker, or a complete account-aggregation service. If my main goal is to see where my money goes each week, a budgeting app is the better first choice. If I need investment analysis, I would look to an investment-focused service instead.
I would also be cautious about overinterpreting the score. A score can be useful for tracking direction, but lenders may use different scoring models and information at different times. For that reason, I would view the app as an indicator and preparation aid, not a promise that an application will be approved or offered on particular terms.
How it compares with the usual alternatives
Compared with a bank’s own mobile app, TransUnion® may be more useful when my goal is specifically to inspect credit information rather than manage one bank relationship. A bank app usually wins for balances, transfers, and transactions. This app wins when I want a dedicated credit view, provided that is the task I have in mind.
Compared with a general budgeting app, the difference is even clearer. Budgeting tools help me plan spending and understand cash flow; this app helps me examine credit-related information and offers. I would not ask either category to perform the other’s job. Someone choosing between them should begin with the problem they are trying to solve, not with which app has more screens.
Compared with a credit-card issuer’s score feature, this app can be attractive as a separate place for people who do not want their monitoring routine tied to one card provider. On the other hand, a card issuer’s tool may be more convenient for someone who already lives in that issuer’s app and only wants a quick score glance. The better choice depends on whether I value a dedicated credit workflow or maximum convenience inside an existing financial relationship.
Compared with checking a report only when applying for credit, regular access is more proactive. The trade-off is that I must build a habit and learn how to read what I see. For a person who wants no ongoing involvement, an occasional official report review may be enough. For someone who wants earlier awareness, this app is the more practical companion.
When switching is worth the effort
Switching to this app makes sense if my current routine is fragmented: perhaps I check a score in one place, search for report details somewhere else, and evaluate offers without a consistent record. Bringing those tasks closer together can reduce the chance that I overlook a change or forget why I opened the report.
The cost of switching is mostly behavioral. I need to create another routine, become comfortable with the app’s navigation, and decide how I will handle information that needs correction. If my existing bank app already gives me everything I need for a quick check, moving may not add enough value. I would switch because I want a dedicated credit perspective, not simply because I want another finance icon on my phone.
I would also consider the timing. I would not make a new app my only source of information the day before a major application. I would install it earlier, learn the workflow, and compare what I see with my own financial records. That gives me room to understand the report and deal with questions without unnecessary pressure.
Who should use it and who should skip it
I would recommend TransUnion® to people who want a free, focused way to check scores and reports, especially before an important financial decision. It is also a reasonable fit for someone building a first credit-monitoring habit and for anyone who wants offers visible alongside credit information while still planning to compare them independently.
I would be more hesitant to recommend it to someone seeking a complete money-management center. If budgeting, subscription tracking, investment performance, or daily cash-flow planning is the priority, another category will serve that person better. I would also suggest caution for anyone who becomes anxious by checking credit too often; a scheduled review is healthier than repeatedly refreshing a number.
People who expect instant explanations for every score movement may also be disappointed. The app can organize information, but understanding a change still requires reading the report and considering reporting timing. That is not a reason to reject it, but it is an important expectation to set before relying on it.
My recommendation
After using it as a decision aid rather than a financial oracle, I see TransUnion® as a useful specialist app with a clear purpose. Its best feature is the connection between score checking, report review, and offer research. Its main weakness is that the focused experience cannot replace broader financial tools, and the modest average rating tells me I should be prepared for some friction.
My recommendation is to try it if credit awareness is the problem you want to solve. Start with the report, not just the score; keep notes about anything unusual; and compare every offer before acting. If you only need banking, budgeting, or investing features, choose an app designed for those jobs instead.
For me, the deciding factor is whether I can turn the app into a calm, occasional routine. Used that way, it can help me prepare for applications, notice possible errors, and understand my credit picture more clearly. It is not a replacement for responsible financial behavior, but it can be a practical window into the information that influences important decisions.
TransUnion® FAQ
What is the TransUnion® app used for?
The TransUnion® app is designed to help users monitor and understand their credit information from a mobile device. Depending on your location and subscription, it may provide access to credit reports, credit scores, alerts about changes, identity-protection tools, and educational resources. Available features can vary by country, account type, and the specific TransUnion service connected to the app.
Is the TransUnion® app free to download and use?
Downloading the TransUnion® app is generally free, but not every feature is necessarily included at no cost. Basic account access or limited monitoring may be available without payment, while frequent score updates, expanded reports, identity monitoring, and other protection services can require a subscription or trial. Review the pricing, renewal terms, and in-app purchase details before signing up.
Is the TransUnion® credit score shown in the app accurate?
The score displayed in the app is generated from information in your TransUnion credit file and is intended to help you track changes over time. However, it may use a particular scoring model that differs from the score a lender uses when reviewing an application. Because lenders can check different bureaus and models, treat the app score as a useful guide rather than a guarantee of approval.
How does TransUnion® protect my personal and financial information?
TransUnion® uses account security measures intended to protect sensitive information, such as login authentication, encrypted connections, and identity-verification procedures. Even with these safeguards, users should create a strong, unique password, avoid accessing the account on unsecured public networks, keep the app updated, and enable available security options. Never share verification codes or login details with anyone.
What should I do if I find an error or suspicious activity in my TransUnion® report?
If your report contains inaccurate information, review the details carefully and use TransUnion’s available dispute process through the app or its official website. You may need to provide supporting documents and explain why an entry is incorrect. For unfamiliar accounts, inquiries, or possible identity theft, contact TransUnion promptly and consider notifying the relevant creditor and appropriate authorities.











